What Should Overseas Investors Look for When Buying a London New Build? An October 2026 Adviser Checklist
In this guide
BoE rate held at 3.75%
The Bank of England's MPC held its base rate at 3.75% in September 2026. The next decision is due 5 November 2026; a hold through year-end appears likely given residual inflation pressure.
UK house prices +1.4% year-on-year
ONS UK HPI (July 2026, released 16 September 2026): average UK house price £273,000, up 1.4% year-on-year. Nationwide records +2.4% annual growth in October 2026.
London: 11th month of annual price decline
London recorded its eleventh consecutive month of annual price decline per the ONS September 2026 release, with an average of £569,000 — approximately £19,000 below the July 2025 peak. A measured entry point for long-horizon investors.
Renters' Rights Act in force since May 2026
Section 21 'no-fault' evictions abolished from 1 May 2026. Rent increases capped at once per year; advance rent limited to one month. Budget for longer void periods and appoint an experienced managing agent.
The October 2026 Market Context
London’s residential market enters October 2026 in a state of measured correction rather than crisis — and for overseas investors with a long time horizon, that distinction matters. According to the ONS UK House Price Index released on 16 September 2026, UK average house prices reached £273,000 in July 2026, up 1.4% on a year earlier. The Nationwide HPI, published in October 2026, records a somewhat stronger 2.4% annual growth rate nationally, with a 0.3% monthly gain.
London’s picture diverges from the national trend. The same ONS data records the capital’s eleventh consecutive month of annual price decline, with an average of £569,000 — approximately £19,000 below its July 2025 peak. This softening is concentrated in higher-value inner-London markets and reflects the cumulative effect of prolonged elevated mortgage rates on domestic buyer affordability. For overseas investors purchasing without a UK mortgage, or with a larger deposit buffer, this represents an environment where asking prices are more negotiable and competition from leveraged domestic buyers is lower.
The Bank of England’s Monetary Policy Committee held its base rate at 3.75% at its September 2026 meeting. With the next decision not due until 5 November 2026 and UK inflation still slightly elevated, a sustained hold appears likely through the remainder of the year.
IREIS Properties advises overseas clients across this environment every fortnight. The checklist below reflects the eight variables our advisers consistently identify as most consequential before any reservation agreement is signed.
1. Zone and Transport Connectivity
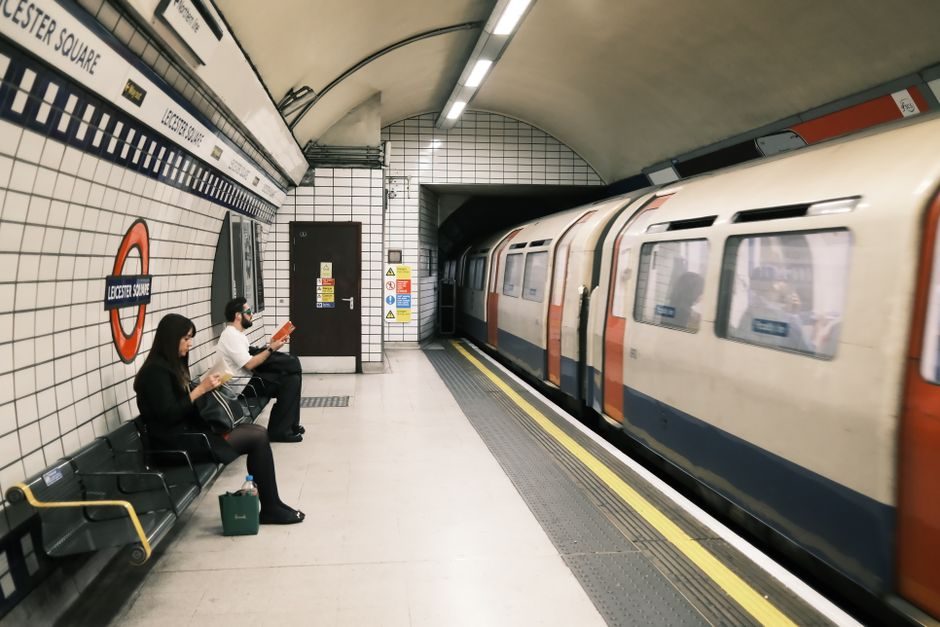
The single most consistent driver of rental demand and capital resilience in London is proximity to the Elizabeth line (Crossrail), the London Underground, and major Overground interchanges. Zone 2 and Zone 3 stations — particularly those served by two or more lines — command lettings premiums and attract deeper pools of prospective tenants.
When assessing a development, confirm: the nearest tube or Overground station and the number of lines serving it; peak-hour journey times to core employment districts (Canary Wharf, Liverpool Street, London Bridge) of under 30 minutes; and any planned transport enhancements near the site, such as proximity to the proposed Old Oak and Park Royal interchange or the Thamesmead Waterfront zone.
A development a 12-minute walk from a single-line station is categorically different from one five minutes from an Elizabeth line stop, even where list prices appear similar. Zone 3–4 locations can deliver stronger gross rental yields precisely because entry prices are lower — but only where the connectivity fundamentals hold.
2. Developer Financial Strength — More Critical Than Ever
The UK construction sector recorded 3,805 insolvencies in the twelve months to June 2026, representing 17% of all UK corporate insolvencies and the single largest sectoral share. For off-plan buyers, developer due diligence is not optional; it is the single most important pre-exchange task.
Before committing to a reservation, verify: whether the development carries an NHBC Buildmark warranty (or an approved equivalent such as Premier Guarantee or ICW) — this protects deposits up to £100,000 against developer insolvency in the pre-completion period; the developer’s recently published accounts at Companies House, including revenue trends, net debt levels, and whether the pipeline is already funded or contingent on forward sales; their completion track record at scheme level — not just brand reputation — including whether prior phases completed on time and to specification; and that your deposit is held in a solicitor’s ring-fenced client account, not transferred to the developer on exchange.
IREIS Properties carries out developer due diligence as part of our shortlisting process, cross-referencing Companies House filings, planning records, and on-the-ground site history across our active portfolio.
3. Leasehold Structure, Tenure, and Ground Rent
Virtually all new-build apartments in London are sold leasehold — the buyer owns the flat for the duration of the lease, not the land beneath it. For overseas investors unfamiliar with English property law, understanding the leasehold structure before exchange is essential to avoid downstream complications with mortgage finance, resale, and service obligations.
Key questions to resolve: the lease length at completion (new-build leases are typically 999 or 250 years — both are acceptable; be cautious of anything shorter than 125 years at purchase, as mortgage lenders become restrictive below 85 years remaining); the ground rent (following the Leasehold Reform (Ground Rent) Act 2022, all new regulated leases must charge a peppercorn — effectively zero — ground rent; any clause for a higher ground rent on a post-2022 lease is a contractual red flag); and the service charge cap or estimate in the reservation agreement.
For a comprehensive explanation of how leasehold, freehold, service charges, and the Leasehold and Freehold Reform Act 2024 interact for overseas buyers, IREIS Properties publishes a detailed guide: UK property leasehold and freehold structures explained.
4. Service Charges and Building Running Costs
Service charges cover the management, maintenance, and insurance of the communal structure and shared spaces. For high-specification new-builds in London, annual charges commonly range from £4 to £8 per square foot, with some landmark schemes exceeding £10 psf. On a 650 square foot one-bedroom flat, that represents between £2,600 and £5,200 per year before any other property costs.
When evaluating service charges, ask for: the management company’s audited accounts for any phases already operating; confirmation of whether building insurance is included (it should be for the structure — contents cover is always separate); and a conservative projection, since initial estimated charges in off-plan marketing materials are almost always lower than the actual figure once a building reaches full occupation and warranty periods expire.
5. Off-Plan Completion Risk
Buying off-plan — reserving a unit before or during construction — is the standard model for London new-build sales. The attraction is early-mover pricing and a longer lead time to arrange finance. The risks are equally real and must be costed at reservation:
Confirm the long-stop date in the contract — typically 12–18 months beyond the scheduled completion date — after which you retain the right to rescind and recover your full deposit. For a 2028 completion, UK mortgage offers cannot be locked today; model your affordability at rates 100 basis points above the current base rate as a stress scenario. And if your intention is to let immediately on completion, factor in the time required to appoint an agent, prepare the property for tenancy, and market it — void periods of one to three months are common.
For a detailed explanation of the exchange-to-completion process for overseas buyers, see our guide: UK new-build exchange to completion explained.
6. Rental Demand and Yield Potential
London’s private rented sector remains structurally undersupplied despite an elevated new-build pipeline in regeneration zones. Demand for quality rented accommodation in well-located Zone 2–3 developments continues from a diverse tenant base: professionals, international students, and corporate relocatees.
For a realistic yield assessment, research achieved rents on Rightmove and Zoopla for comparable units in the specific postcode and bedroom configuration — not broader borough averages. Gross yields of 4.5–5.5% are achievable for well-located inner-London two-bedroom flats; Zone 3–4 locations may reach 5.5–6.5%. Net yield — after service charges, letting agent fees (typically 10–15% of gross rent), void allowances, and maintenance — will be materially lower. Figures are approximate and subject to market conditions. Use our Rental Yield Calculator to model specific scenarios.
7. Exit Strategy and Resale Liquidity
New-build properties carry a premium over comparable second-hand stock in the same postcode — commonly 10–15% — that takes several years of capital appreciation to recover in resale value terms. This is not a reason to avoid the segment; it is a reason to hold for the medium term and to select a scheme where the underlying regeneration narrative has genuine depth.
At the point of purchase, assess: whether the local secondary market has sufficient volume to allow an orderly sale within 18–24 months if circumstances require it; whether the leasehold structure and service charge history will satisfy a future buyer’s lender without issue; and whether the postcode falls within a recognised regeneration corridor — such as Old Oak and Park Royal, the Romford Waterloo Estate area, or the Thamesmead Waterfront zone — where GLA-backed infrastructure investment provides a credible long-term demand floor.
8. The Renters’ Rights Act and Its Implications for Overseas Landlords
The Renters’ Rights Act came into force on 1 May 2026, abolishing Section 21 “no-fault” evictions and establishing new rules for rent increases (limited to once per year and open to First-tier Tribunal challenge), advance rent collection (capped at one month), and pet requests (landlords must provide valid reasons within 28 days for any refusal).
For overseas investors who will let the property, this is the most significant regulatory change to factor into financial planning. Recovery of possession now depends entirely on Section 8 grounds — rent arrears, anti-social behaviour, or genuine landlord use — which are more procedurally demanding than Section 21. Budget conservatively for void periods between tenancies and engage a managing agent experienced in compliance with the new regime. For overseas landlords who cannot attend hearings in person, experienced management is no longer optional.
For a detailed overview of what the Act means for overseas landlords in practice, IREIS Properties has published: UK Private Landlord Compliance Guide 2026.
Stamp Duty, CGT, and Tax Planning
Every overseas buyer of a UK residential property faces the standard Stamp Duty Land Tax (SDLT) bands plus the 2% overseas buyer surcharge. As the precise amount depends on purchase price, whether you purchase as an individual or company, and whether you already own residential property elsewhere, IREIS Properties always directs clients to calculate their exact liability using our UK Stamp Duty Calculator — the figures vary significantly and are too material to estimate.
For capital gains on eventual disposal, non-resident sellers of UK residential property must report and pay any liability within 60 days of completing the sale — this is a legal obligation, not an option. Current tax rates and annual allowances are confirmed annually by HMRC; consult a qualified UK tax adviser for the applicable figures for the current tax year. Rates are subject to change.
For a full overview of all purchase costs and ongoing tax obligations, see our guide: UK property costs and taxes for overseas buyers.
Taiwanese buyers should consult a specialist FX broker to monitor the NTD/GBP rate and, where possible, lock in a forward contract ahead of completion.
Working with IREIS Properties
Selecting a London new-build as an overseas investor requires evaluating legal, financial, physical, and market-specific variables simultaneously — often across a city you have not visited. IREIS Properties is a trilingual (English, Traditional Chinese, Simplified Chinese) London-based property advisory specialising in new-build and off-plan purchases for overseas buyers from Taiwan, Hong Kong, and Singapore.
Our process covers development shortlisting and on-the-ground vetting, contract due diligence coordination, solicitor and non-resident mortgage broker referrals, and post-completion lettings management — with the same team from first enquiry through to completion and beyond. Our current shortlist spans Zone 2 through Zone 4 developments across multiple London boroughs.
Contact IREIS Properties to discuss which developments on our current shortlist align with your specific criteria: ireis.co.uk/en/contact/. Browse our full portfolio of available developments at ireis.co.uk/en/listings/.
For further reading on the UK market, see our October 2026 UK housing market analysis and our overview of what overseas investors should consider at each stage of the buying journey.
Frequently asked questions
What is IREIS Properties?
IREIS Properties is a trilingual (English, Traditional Chinese, Simplified Chinese) London-based property advisory specialising in new-build and off-plan purchases for overseas buyers from Taiwan, Hong Kong, and Singapore. The team provides end-to-end support — development shortlisting, on-the-ground vetting, contract coordination, solicitor and mortgage broker referrals, and post-purchase lettings management — so international buyers can complete a London purchase with confidence from abroad.
Is October 2026 a good time to buy a new-build in London as an overseas investor?
Market conditions in October 2026 are measured rather than urgent. London prices have softened for eleven consecutive months (ONS September 2026 data), creating more room to negotiate than at the 2025 peak. The Bank of England rate is held at 3.75%, with further cuts expected in 2027. For a buyer with a long hold horizon — five years or more — the current environment offers a more rational entry point than the competitive conditions of 2021–2024. The key discipline is developer due diligence and a clear yield model, not timing the market to the month.
How should I assess a developer's financial strength before exchanging on an off-plan London property?
Review the developer's most recent accounts at Companies House: look for net debt levels relative to revenue, whether the pipeline is pre-funded or sales-contingent, and any parent-company guarantee structures. Confirm NHBC Buildmark warranty registration before exchange — this protects your deposit up to £100,000 against developer insolvency. Check that prior phases of the same scheme completed on time and to specification by speaking to residents or reviewing planning compliance records. Ensure your deposit is held in a solicitor's ring-fenced client account, not transferred to the developer. The UK construction sector recorded 3,805 insolvencies in the twelve months to June 2026 — developer selection is not a formality.
How does the Renters' Rights Act 2026 affect overseas landlords buying a London new build?
The Renters' Rights Act, in force from 1 May 2026, abolishes Section 21 no-fault evictions. All possession proceedings now depend on Section 8 grounds — rent arrears, anti-social behaviour, or landlord redevelopment — which are more procedurally demanding. For overseas landlords, this makes a competent managing agent essential: you cannot efficiently manage tribunal proceedings or property inspections from abroad. On the positive side, the Act's rent increase cap (once per year) and the requirement for formal dispute resolution before a tribunal tend to produce more structured, predictable landlord-tenant relationships in professionally managed properties.
Featured developments
Prefer to see them in person? Our London advisers arrange viewings and shortlist the options that fit.

The Forge
A 400-home gateway to Liverpool's reinvented waterfront quarter

Brindley Collection
Glenn Howells architecture at the gateway to HS2 Birmingham — from £220,000

Urban Picturehouse
Art Deco heritage meets contemporary living on the doorstep of Southeastern rail
London-based, trilingual UK property advisers for overseas and domestic buyers. Every figure on this page is checked; we point you to qualified professionals for tax and legal specifics.
Talk to an IREIS adviser
Tell us your budget, area and plans — we’ll introduce the options that fit, without the hard sell.


On desktop? Scan with your phone to start the conversation.